Deprecated: Creation of dynamic property WP_Term::$cat_ID is deprecated in /home/uathvgwk/domains/rysiek.frydryk.pl/public_html/wp-includes/category.php on line 378
Deprecated: Creation of dynamic property WP_Term::$category_count is deprecated in /home/uathvgwk/domains/rysiek.frydryk.pl/public_html/wp-includes/category.php on line 379
Deprecated: Creation of dynamic property WP_Term::$category_description is deprecated in /home/uathvgwk/domains/rysiek.frydryk.pl/public_html/wp-includes/category.php on line 380
Deprecated: Creation of dynamic property WP_Term::$cat_name is deprecated in /home/uathvgwk/domains/rysiek.frydryk.pl/public_html/wp-includes/category.php on line 381
Deprecated: Creation of dynamic property WP_Term::$category_nicename is deprecated in /home/uathvgwk/domains/rysiek.frydryk.pl/public_html/wp-includes/category.php on line 382
Deprecated: Creation of dynamic property WP_Term::$category_parent is deprecated in /home/uathvgwk/domains/rysiek.frydryk.pl/public_html/wp-includes/category.php on line 383

Current liabilities are debts typically due for repayment within one year, including accounts payable and taxes payable. Long-term liabilities are obligations that are due for repayment in periods longer than one year, such as bonds payable, leases, and pension obligations. A company’s accounting policies can change the calculation of its debt-to-equity. For example, preferred stock is sometimes included as equity, but it has certain properties that can also make it seem a lot like debt. Specifically, preferred stock with dividend payment included as part of the stock agreement can cause the stock to take on some characteristics of debt, since the company has to pay dividends in the future. Therefore, even if such companies have high debt-to-equity ratios, it doesn’t necessarily mean they are risky.
How to Calculate Shareholders Equity
- But utility companies have steady inflows of cash, and for that reason having a higher D/E may not spell higher risk.
- Liabilities are obligations that the company owes to external parties, such as loans, accounts payable, and accrued expenses.
- Total Equity (TE) is the value remaining for shareholders after deducting liabilities from assets.
- It’s easy to get started when you open an investment account with SoFi Invest.
- It is possible that the debt-to-equity ratio may be considered too low, as well, which is an indicator that a company is relying too heavily on its own equity to fund operations.
They represent returns on total stockholders' equity reinvested back into the company. In some cases, companies can manipulate assets and liabilities to produce debt-to-equity ratios that are more favorable. If they’re low, it can make sense for companies to borrow more, which can inflate the debt-to-equity ratio, but may not actually be an indicator of bad tidings. Many startups make high use of leverage to grow, and even plan to use the proceeds of an initial public offering, or IPO, to pay down their debt. The results of their IPO will determine their debt-to-equity ratio, as investors put a value on the company’s equity. Analysts and investors use this metric to determine if a company uses equity or investment cash to profit efficiently and effectively.
IPOs and Debt-to-Equity Ratios

If a 2-liter bottle of store-brand cola costs $1 and a 2-liter bottle of Coke costs $2, then Coca-Cola has brand equity of $1. Home equity is often an individual’s greatest source of collateral, and the http://allmedia.ru/newsitem.asp?id=681428 owner can use it to get a home equity loan, which some call a second mortgage or a home equity line of credit (HELOC). An equity takeout is taking money out of a property or borrowing money against it.
Retained Earnings Calculation Example (RE)
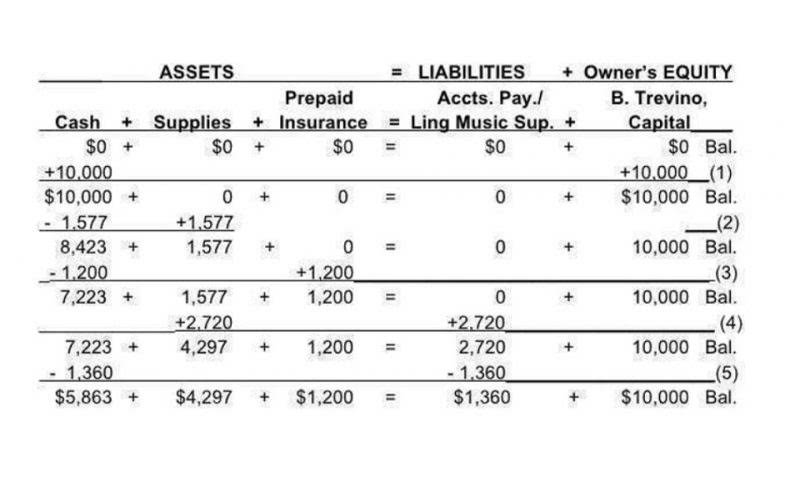
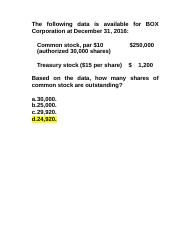
The equity Formula states that the total value of the company’s equity is equal to the sum of the total assets minus the total liabilities. The retained earnings portion reflects the percentage of net earnings that were not paid to shareholders as dividends and should not be confused with cash or other liquid assets. The number of shares http://www.myasnoy-soyuz.ru/news/10-gana-mestnye-pticevody-vstupili-v-borbu-s-inostrannymi-konkurentami.html issued and outstanding is a more relevant measure than shareholder equity for certain purposes, such as dividends and earnings per share (EPS). This measure excludes Treasury shares, which are stock shares owned by the company itself. If a company’s shareholder equity remains negative, it is considered to be balance sheet insolvency.
Treasury Shares
Such an agreement prevents the borrower from taking on too much new debt, which could limit the original creditor’s ability to collect. In order to calculate the debt-to-equity ratio, you need to understand http://amxxmodx.ru/amxmodx_plugins/statistical/545-plagin-vyvodit-v-hud-informaciyu-o-igroke.html both components. First and foremost, SoFi Learn strives to be a beneficial resource to you as you navigate your financial journey.We develop content that covers a variety of financial topics.


Deprecated: Creation of dynamic property WP_Term::$cat_ID is deprecated in /home/uathvgwk/domains/rysiek.frydryk.pl/public_html/wp-includes/category.php on line 378
Deprecated: Creation of dynamic property WP_Term::$category_count is deprecated in /home/uathvgwk/domains/rysiek.frydryk.pl/public_html/wp-includes/category.php on line 379
Deprecated: Creation of dynamic property WP_Term::$category_description is deprecated in /home/uathvgwk/domains/rysiek.frydryk.pl/public_html/wp-includes/category.php on line 380
Deprecated: Creation of dynamic property WP_Term::$cat_name is deprecated in /home/uathvgwk/domains/rysiek.frydryk.pl/public_html/wp-includes/category.php on line 381
Deprecated: Creation of dynamic property WP_Term::$category_nicename is deprecated in /home/uathvgwk/domains/rysiek.frydryk.pl/public_html/wp-includes/category.php on line 382
Deprecated: Creation of dynamic property WP_Term::$category_parent is deprecated in /home/uathvgwk/domains/rysiek.frydryk.pl/public_html/wp-includes/category.php on line 383

Then categorize your expenses into different categories, start estimating your expected revenue for the upcoming period, and allocate your expenses accordingly. There are several effective ways to manage bookkeeping responsibilities in-house or externally by using helpful tools and technologies. Bookkeeping beginners need quick wins to get started quickly and efficiently. The tips below are industry standards that will help any small business excel at bookkeeping.

Choose your bookkeeping method
If you’re comfortable with your current software, ensure your bookkeeping service supports it. To track your business’s financial health, having a bookkeeping system can help you stay organised and aware of where you stand each week and month. A schedule can include paying vendors at a specified time each month, reconciling monthly bank statements, recording revenue weekly, and making regularly scheduled bank deposits. Accounting software, including cloud-based programs, is changing the way businesses complete accounting tasks. In some cases, small business owners may be able to do their own accounting, especially with the use of software.
- Before you take on any small-business bookkeeping tasks, you must decide whether a single- or double-entry accounting system is a better fit.
- Doola’s bookkeeping services seamlessly integrate with your contracts, ensuring that all financial transactions align with your legal agreements.
- To set up a budget, gather your financial data, such as income statements, balance sheets, and cash flow statements.
- Professional associations also offer certifications so that you can hone your skills and market yourself as a professional bookkeeper.
When is it time to hire an accountant?
Will your business be generating invoices, cost estimates, or billing statements? You’ll be responsible for accurate payments to employees and taxing authorities. With tax codes frequently changing, it’s important to ensure you follow https://автобог-томск-запчасти.рф/rus/index.php the most current laws and regulations. Bookkeeping is essential to the vitality and long-term success of any small business. Primarily, you need to have an accurate picture of all the financial ins and outs of your business.

Ready to learn more about accounting?
Any purchases you make or money you spend on the operation of your business (toward things like supplies, utilities, or advertising) goes under expenses. When it comes to budgeting for bookkeeping, the difference hinges on whether you hire or manage using software tools. Although bookkeeping is an investment, it’s generally much more affordable https://www.a-bcd.ru/press/61134/ than attempting to correct costly mistakes down the road. With this type of service, you can communicate completely by email or phone without having to set aside time to meet in person. The responsibilities handled by a service will depend on the provider, so be sure to discuss the scope of work and compare options to find the right fit.
Best Accounting Software for Small Businesses of 2024
We’ll show you examples of how to record a transaction as both a credit and debit later on. If she’d kept her financial records tight and invoiced according to the contract, she could’ve kept https://vsplanet.net/superstars/nickkhan/ that cash flowing smoothly and her client happy. Don’t forget to sync these dates with your bookkeeping records so that you can easily cross-reference payments with contract milestones.

How to do bookkeeping for small businesses: A step-by-step guide
- In all cases, your business needs to exceed the threshold for taxes for two consecutive years.
- As your business grows and you hire employees, you can consider whether to rent office space or keep working remotely.
- This guide covers bookkeeping fundamentals, resources to streamline the process, and critical bookkeeping tasks.
- Your cash flow statement helps you understand how money moves into and out of your business.
- We also looked at real customer experiences to determine if their expectations were met based on what each company promised.
How much does a bookkeeping service cost?
]]>Deprecated: Creation of dynamic property WP_Term::$cat_ID is deprecated in /home/uathvgwk/domains/rysiek.frydryk.pl/public_html/wp-includes/category.php on line 378
Deprecated: Creation of dynamic property WP_Term::$category_count is deprecated in /home/uathvgwk/domains/rysiek.frydryk.pl/public_html/wp-includes/category.php on line 379
Deprecated: Creation of dynamic property WP_Term::$category_description is deprecated in /home/uathvgwk/domains/rysiek.frydryk.pl/public_html/wp-includes/category.php on line 380
Deprecated: Creation of dynamic property WP_Term::$cat_name is deprecated in /home/uathvgwk/domains/rysiek.frydryk.pl/public_html/wp-includes/category.php on line 381
Deprecated: Creation of dynamic property WP_Term::$category_nicename is deprecated in /home/uathvgwk/domains/rysiek.frydryk.pl/public_html/wp-includes/category.php on line 382
Deprecated: Creation of dynamic property WP_Term::$category_parent is deprecated in /home/uathvgwk/domains/rysiek.frydryk.pl/public_html/wp-includes/category.php on line 383
Content
- Taxation
- Accounting software for wholesalers and wholesales businesses
- About Distribution and Wholesale Industry Accounting Services
- Secure Your Financial Records
- Upgrade your Wholesale business with double-entry accounting from Vencru
- Compliance with tax laws:-
Multi-location inventory capabilities allow you to track items across multiple warehouses and automatically sync that information with your financial data. You can now customize your FreshBooks experience with a range of business-friendly apps. Take control of your business accounting with the help of these integrations. Because accounting for wholesale distribution usually transfers a considerable amount of merchandise in and out of their warehouses…
Is Nike a wholesaler?
Nike initiated its pullback from wholesale distribution in 2021, a year in which the world was still ensnared in a global pandemic and one in which e-commerce provided an ample tailwind behind nearly every retailer's back.
This secure online payment platform allows your clients to pay in minutes. If you have recurring customers, they are welcome to create an account and keep a credit card on file. If they choose this option, the card will be charged within moments of receiving the invoice.
Taxation
Therefore, today’s distributors must recognize the hidden cost of carrying excess, slow-moving or obsolete inventories. Your company should strive to attain an optimal balance between minimizing inventory levels and maintaining a sufficient quantity of stock to satisfy customer needs. Freight costs and transportation logistics can also significantly impact your company’s profitability.
This can save you time and effort by eliminating the need to manually enter the same transaction repeatedly. Keeping track of all your wholesale business’s finances might be difficult, but syncing your bank statements can help. Request that your bank synchronize all of your statements at the end of the month. Keep all your business’s financial records secured, more especially consider storing all your files offsite in the event of any natural disaster or fire.
Accounting software for wholesalers and wholesales businesses
Create a professional impression on your customers and suppliers with Vencru with our customized and professional invoices, receipts, and purchase order. Vencru allows https://www.bookstime.com/articles/wholesale-accounting you to incorporate your wholesale business’ unique branding by adding a business logo. The distribution company normally keeps its inventory as an asset valued at cost.
You need cloud accounting software for your wholesale business that simplifies the bookkeeping process. That way, you can spend more time making sales and growing your business and less time tied down to a desk. FreshBooks offers best-in-class accounting tools designed with your small business in mind, so you can ditch the complicated calculations and time-consuming spreadsheets. Its suite of products works together to offer a streamlined accounting software that keeps your finances in order, even when you’re busy closing another sale.
About Distribution and Wholesale Industry Accounting Services
International Tax Practitioners has the financial tools you need to cultivate an expanding international business. We have years of experience working with wholesale distribution businesses, so we truly understand accounting and tax planning for your industry. Over the past decade, distribution and wholesale companies have had to address the needs of considerably different supply chains, customers and vendors. Many distribution and wholesale companies have had to become more efficient, while facing more stringent cost demands, delivery requirements, and the unbundling of services. Some of the challenges facing distributors and wholesalers entail a mix of marketing, accounting, tax and operational issues. At Newburg CPA, we can help you navigate the accounting, operational and tax and compliance related matters that are unique to the distribution and wholesale industries.
- This secure online payment platform allows your clients to pay in minutes.
- Our complete line of accounting services include traditional accounting and tax services in conjunction with insightful financial analysis and business advisory.
- BPM works with more than 100 wholesalers and distributors to provide timely business advice and valuable solutions to complex challenges.
- Request that your bank synchronize all of your statements at the end of the month.
- Vencru provides insight into business performance with double entry accounting reports.
- Mismanaged inventory can lead to missed opportunities, lost customers and higher costs — problems that become exponentially larger when you have…
Do you have employees in your store and you are aware of how you can pay them using your QuickBooks? Well, QuickBooks have the option to create a payroll schedule for your employees. Controlling costs and keeping pace with evolving technology and competitive pressure in creating that product is the key to any manufacturer’s success.
]]>Deprecated: Creation of dynamic property WP_Term::$cat_ID is deprecated in /home/uathvgwk/domains/rysiek.frydryk.pl/public_html/wp-includes/category.php on line 378
Deprecated: Creation of dynamic property WP_Term::$category_count is deprecated in /home/uathvgwk/domains/rysiek.frydryk.pl/public_html/wp-includes/category.php on line 379
Deprecated: Creation of dynamic property WP_Term::$category_description is deprecated in /home/uathvgwk/domains/rysiek.frydryk.pl/public_html/wp-includes/category.php on line 380
Deprecated: Creation of dynamic property WP_Term::$cat_name is deprecated in /home/uathvgwk/domains/rysiek.frydryk.pl/public_html/wp-includes/category.php on line 381
Deprecated: Creation of dynamic property WP_Term::$category_nicename is deprecated in /home/uathvgwk/domains/rysiek.frydryk.pl/public_html/wp-includes/category.php on line 382
Deprecated: Creation of dynamic property WP_Term::$category_parent is deprecated in /home/uathvgwk/domains/rysiek.frydryk.pl/public_html/wp-includes/category.php on line 383
Clio Payments lets Clio Manage users offer a range of payment options, from online credit card payments to eCheck payments to installment plans. It handles all trust-related transactions in compliance with IOLTA rules and uses the payment industry’s most advanced security measures. Breaking payments into smaller, more manageable installments benefits both firms and their clients. Paper bills can get lost in the mail, and receiving an invoice months after the work has been completed is frustrating for clients. Digital payments are also easy to schedule in advance, making it easy to set up future or recurring payments. Electronic invoices also help firms save costs, by eliminating time spent on preparing bills and reducing the use of paper and stamps.
What is a law firm accounts receivable process?
Maintaining good client relationships is a top priority for any attorney. Calling clients for payment follow-ups, sending snail mail, and other manual A/R processes can create a lot of unwelcome stress and tension. If a practice has limited or inflexible payment options that make it inconvenient or difficult for clients to pay, it can make the situation even worse. Being proactive about collecting payments is a key part of accounts receivable management. Start by providing clear communication channels for customers to ask questions about invoices or payments.
Streamline Your Law Firm Invoice Process With Digitslaw
We know you give your best while working on a case, and it’s a bit disheartening when all your hard work goes down the drain as you send out the bills but get no payment or response. Do you want to see your unpaid bills piling up like the cases you bag? If not, it’s time to revamp your law firm’s accounts Law Firm Accounts Receivable Management receivable processes. Given these challenges, effective accounts receivable management is crucial for law firms. By streamlining the invoicing process, offering convenient payment options, and implementing timely follow-ups on overdue accounts, firms can reduce their AR balance and improve liquidity.
Increase Your Billable Hours: Seven Tactics for Optimizing Your Time
- Accounts receivable (AR) represents the total amount of money clients owe to the law firm for services provided but not yet paid.
- We use the insights gained from this assessment to begin identifying opportunities for increased revenue realization.
- Establishing open communication with your client is important to ensure your law firm’s accounts receivable management is smooth.
- Additionally, call every client who has not paid a prior month’s invoice and ask for payment.
If multiple people are working on the matter, add additional details such as their name, title, and hourly rate specific to the services they performed. Stay on top of matters, communicate with clients, and view documents from your smartphone or any device with an internet connection. Perhaps the client did so in error, having not recognized the transaction and mistakenly deemed it to be fraudulent. Our experience at all stages of the patent process gives us unique insights and advantages in patent litigation. Brian attended Texas A&M University and is a member of the ETAPL and AAPL. He has 17 years of experience as a Petroleum Landman and is expert in Project Management, title research, mineral leasing, runsheet preparation, seismic permitting, and right-of-way leasing.
Modernizing your practice’s A/R processes is essential to meeting today’s client expectations and increasing revenue. Between tracking billable hours, retaining and invoicing clients, and complying with stringent legal and ethical requirements, law firms have unique and complex billing needs. Solicitors deserve to be paid on time for the valuable work they do—and when you’re running a busy practice, you don’t want to waste time chasing down clients for payment. Therefore, law firms must develop effective accounts receivable processes. Attorneys deserve to be paid on time for the valuable work they do—and when you’re running a busy practice, you don’t want to waste time chasing down clients for payment. Law firm accounts receivable (AR) refers to the money clients owe your firm for legal services you’ve already provided.
Is Confidential Data at Your Law Firm Really Secured?
- She also volunteers with Junior Achievement in Tyler as well as Cain Elementary in Whitehouse, Texas.
- With an online payment service provider, it’s easy to monitor and manage A/R in real-time, without the paper trail.
- Let’s say you’ve collected $90,000 in a given year, off of $110,000 in billings.
- Second, you need to minimise the time you spend following up on late payments.
- After all, you need to have steady, dependable cash flow to maintain a healthy practice and the income that comes with that.
- There are several steps firms can take to reduce the time they spend chasing up late payments and make life as easy as possible for their clients.
- You might be familiar with the term ‘accounts receivable,’ which simply refers to the money customers owe a business for the goods or services it provides.
There are several steps firms can take to reduce the time they spend chasing up late payments and make life as easy as possible for their clients. What’s more, with tools like Clio Manage, you can resolve potential chargebacks from one single portal in no time. The reality is that law firms are businesses, and businesses need cash flow to survive and thrive. The efficiency of a law firm’s accounts receivable process is fundamental to profitability.
You could also send a written notice that you’ll turn the account over to collections when it reaches 90 days past due. Billing software built for lawyers also minimizes the time you spend on non-billable tasks and ensures https://www.bookstime.com/ compliant handling of trust accounts. Believe it or not, your accounts receivable process begins with the first client consultation. Lawyers experience this all too often—on cases that no one intended to be pro bono.
FOLLOW OUR INDUSTRY BLOG FOR HELPFUL INFORMATION
]]>Deprecated: Creation of dynamic property WP_Term::$cat_ID is deprecated in /home/uathvgwk/domains/rysiek.frydryk.pl/public_html/wp-includes/category.php on line 378
Deprecated: Creation of dynamic property WP_Term::$category_count is deprecated in /home/uathvgwk/domains/rysiek.frydryk.pl/public_html/wp-includes/category.php on line 379
Deprecated: Creation of dynamic property WP_Term::$category_description is deprecated in /home/uathvgwk/domains/rysiek.frydryk.pl/public_html/wp-includes/category.php on line 380
Deprecated: Creation of dynamic property WP_Term::$cat_name is deprecated in /home/uathvgwk/domains/rysiek.frydryk.pl/public_html/wp-includes/category.php on line 381
Deprecated: Creation of dynamic property WP_Term::$category_nicename is deprecated in /home/uathvgwk/domains/rysiek.frydryk.pl/public_html/wp-includes/category.php on line 382
Deprecated: Creation of dynamic property WP_Term::$category_parent is deprecated in /home/uathvgwk/domains/rysiek.frydryk.pl/public_html/wp-includes/category.php on line 383
So, for example, if your Schedule SE says you owe $2,000 in self-employment tax for the year, you’ll need to pay that money when it’s due during the year, but at tax time $1,000 would be deductible on your 1040. Estimated tax is the method used to pay Social Security and Medicare taxes and income tax, because you do not have an employer withholding these taxes for you. Form 1040-ES, Estimated Tax for IndividualsPDF, is used to figure these taxes.
Schedule C InstructionsPDF may be helpful in filling out this form. As a self-employed individual, you may have to file Estimated Taxes quarterly. You can use these estimated tax payments to pay your self-employment tax. Refer to the Estimated Taxes page and Publication 505, Tax Withholding and Estimated Tax for more details on paying your self-employment tax with Estimated taxes.
If your net earnings are below the Social Security wage base:
But for self-employed individuals—whether you have a part-time side gig, full-time freelance work, or a thriving small business—taxes are a regular part of managing your business and personal finances. You can also claim 50 percent of your self-employment tax as an income tax deduction on Form 1040. Determine your net earnings for the year using IRS Schedule C. Enter your gross earnings on the form, and then subtract all deductions, such as business expenses.
But, as a self-employed worker, you act as both your own employee and employer. Because of this, you’re responsible for covering the entire 15.3% of these taxes. Take control of your taxes and get every credit and deduction you deserve. File with H&R Block Online Deluxe (if you have no expenses) or H&R Block Online Premium (if you have expenses). You calculate your self-employment tax on Schedule SE and report that amount in the „Other Taxes” section of Form 1040.
Taxes play a big role in your bottom line
The requirement to pay self-employment tax also extends to W-2 employees who work side hustles. If you drive for Uber only on the weekends or sell the occasional piece of jewelry on Etsy, you’re liable for the full 15.3% — even if FICA taxes are paid through your employer also. An employee’s wage, because it’s received in exchange for time and labor. Self-employed individuals cut out the middleman — the boss — and receive their earnings directly from the customers they serve or sell products to. To file your taxes, you’ll need a Social Security number of an individual taxpayer identification number, better known as your ITIN. You’ll have to follow certain steps when filing your income taxes when you are self-employed.
- If you drive for Uber only on the weekends or sell the occasional piece of jewelry on Etsy, you’re liable for the full 15.3% — even if FICA taxes are paid through your employer also.
- Estimated tax is used for the self-employed since there is no employer to withhold the taxes.
- Self-employment tax consists of Social Security and Medicare taxes for
individuals who work for themselves. - In the same vein, the additional 7.65% freelancers pay to be their own boss is an eligible write-off against their income taxes.
- You’ll pay estimated taxes on April 15, June 15, September 15 and January 15 of the following year.
Subtract the expenses from the income to get your net profit from self-employment. Your net profit is then included on your personal income tax return and taxed in the same way as your other income. If you do work as an independent contractor, you can expect to receive 1099 forms from your clients, reporting the amounts they paid you during the year.
Explore Square and our products
Medicare tax is assessed at a rate of 1.45% for an employer and 1.45% for the employee. Therefore, a self-employed worker is taxed 2.9% (1.45% + 1.45%) as they are considered to be both an employer and an employee. A self-employed person with a total net income of exactly $137,700 in 2022 would have to remit taxes of $21,068.10 ($137,700 x 15.3%). You can deduct half of your self-employment tax on your income taxes.
Self-Employed People Have a Big Tax Payment Due in September … – The Motley Fool
Self-Employed People Have a Big Tax Payment Due in September ….
Posted: Fri, 18 Aug 2023 11:00:28 GMT [source]
The instructions for Schedule SE may be helpful in filling out the form. When you are employed by a business, Social Security and Medicare taxes are split between you and the employer. You pay a little under 8 percent of your gross income toward these taxes, and your employer matches that contribution. Not only are government forms daunting, but learning the ropes of taxation can be truly complicated.
Social Security is equal to 12.4% on the first $147,000 of earnings in 2022, while Medicare is equal to 2.9% on unlimited earnings. Therefore, the combined total self-employment tax may be as high as 15.3%. As a basic example, if you have net self-employed earnings of $ 147,000 in 2022, your self-employment tax would be $22,491. Or, if you want a completely hands off experience, we can even file for you. Learn more about Bench’s small business accounting and tax filing services. While there are some very real benefits to being a freelancer, contractor or business owner, it’s important to know that your taxes are more complicated than they are for salaried workers.
How to calculate quarterly estimated tax payments
Say, for example, that your net self-employment income is $50,000. That’s the amount you report as taxable for income tax purposes on Form 1040. That’s because they’re carrying the full burden of paying for their Social Security and Medicare.
- But when all is said and done, tax deductions can save you from paying the entire tax.
- This post is to be used for informational purposes only and does not constitute legal, business, or tax advice.
- The goal is to pay enough each quarter to make sure you don’t owe too much in taxes when you file on April 15.
- Let’s say you earn $1,500 from a freelance job and claim $500 in deductions.
- You can actively participate in these activities and not be charged self-employment tax.
If you wait to pay the tax until the following April when your annual tax return is due, the IRS may add a penalty charge. Federal law sets the self-employment tax rate at 15.3 percent of net earnings. This rate is the combined total of a 12.4 percent Social Security tax and a 2.9 percent Medicare tax.
Lowering your self-employment taxes with S Corp taxation
As a general rule of thumb, you should aside 15.3% of these reduced net earnings for paying self-employment tax. Second, you can claim 50% of what you pay in self-employment taxes as a self-employment tax deduction on your income. In the above example, you could deduct your taxable income by $7,064.76.

Self-employment tax consists of Social Security and Medicare taxes for
individuals who work for themselves. Employees who receive a W-2 only
pay half of the total Social Security (6.2%) and Medicare (1.45%)
taxes, while their employer is responsible for paying the other half. Self-employed individuals are responsible for paying both portions of
the Social Security (12.4%) and Medicare (2.9%) taxes. If you’re self-employed, however, this is another task you have to take care of yourself. With TurboTax Live Full Service Premium, have a dedicated expert uncover every tax deduction and file your investment and self-employment taxes for you.
What Is the Self-Employment Tax Rate?
This deduction is an adjustment to income claimed on Form 1040, and is available whether or not you itemize deductions. So, you’ve started a business or decided to freelance, and freed yourself from the daily grind of that old job. In fact, you’ll owe tax that you never had to pay as an employee if you made $400 or more in self-employment net income. Form 1040-ES also contains blank vouchers you can use when you mail your estimated tax payments or you may make your payments using the Electronic Federal Tax Payment System (EFTPS).
Shock rise in bogus self-employment in construction – Unite the union
Shock rise in bogus self-employment in construction.
Posted: Tue, 22 Aug 2023 08:10:58 GMT [source]
This number will then be used on Schedule SE (Form 1040), Self-Employment Tax to calculate how much self-employment tax you should have paid throughout the year. The following forms are available for reporting the Self-Employment Tax. To avoid a delay in processing, all forms in this section must be submitted together to the City of Eugene at the address listed on the form, with a separate check or money order for each tax form. Please consult your CPA or tax preparer to ensure accurate calculation of annual net earnings. We know every form you need and every deduction you can take to pay less this year.
I mentioned before that the IRS is stingy about FICA tax, and I wasn’t joking. The IRS makes an additional 7.65% off of the middleman that freelancers did away with. So to ensure they still get their cut, the IRS requires freelance workers to pay both the employer and the employee portions of FICA. When they pay it, it’s known as “self-employment tax” — SE tax for short. Medicare tax is 1.45%, and it’s assessed on all earned income, with no current threshold limits. Wondering whether itemizing your mortgage interest deduction will lower your tax payment?
Self-employed people are responsible for paying the same federal income taxes as everyone else. The difference is that they don’t have an employer to withhold money from their paycheck and send it to the IRS—or to share Self employment tax the burden of paying Social Security and Medicare taxes. Self-employed people must keep track of their own income, estimate how much tax they owe, and in most cases, makes estimated tax payments throughout the year.
]]>Deprecated: Creation of dynamic property WP_Term::$cat_ID is deprecated in /home/uathvgwk/domains/rysiek.frydryk.pl/public_html/wp-includes/category.php on line 378
Deprecated: Creation of dynamic property WP_Term::$category_count is deprecated in /home/uathvgwk/domains/rysiek.frydryk.pl/public_html/wp-includes/category.php on line 379
Deprecated: Creation of dynamic property WP_Term::$category_description is deprecated in /home/uathvgwk/domains/rysiek.frydryk.pl/public_html/wp-includes/category.php on line 380
Deprecated: Creation of dynamic property WP_Term::$cat_name is deprecated in /home/uathvgwk/domains/rysiek.frydryk.pl/public_html/wp-includes/category.php on line 381
Deprecated: Creation of dynamic property WP_Term::$category_nicename is deprecated in /home/uathvgwk/domains/rysiek.frydryk.pl/public_html/wp-includes/category.php on line 382
Deprecated: Creation of dynamic property WP_Term::$category_parent is deprecated in /home/uathvgwk/domains/rysiek.frydryk.pl/public_html/wp-includes/category.php on line 383

One of the most important things to consider when analysing retained earnings is the change in the share of equity amount. If you have a decrease in retained earnings, it may show that your business’s revenue and activities are on the decline. It’s often https://1investing.in/the-role-of-financial-management-in-law-firm/ the most important number, as it describes how a company performs financially. They can boost their production capacity, launch new products, and get new equipment. Or they can hire new sales representatives, perform share buybacks, and much more.
- Revenue is incredibly important, especially for growth companies try to establish themselves in a market.
- Using the example above, the company has $400,000 in retained earnings, so it can expect to get an increase in borrowing capacity of $1.2 or $1.6 million to speed up its growth.
- This amount is adjusted whenever there is an entry to the accounting records that impacts a revenue or expense account.
- It’s often the most important number, as it describes how a company performs financially.
- Retained Earnings are reported on the balance sheet under the shareholder’s equity section at the end of each accounting period.
Public companies have many shareholders that actively trade stock in the company. While retained earnings help improve the financial health of a company, dividends help attract investors and keep stock prices high. The retained earnings are recorded under the shareholder’s equity section on the balance as on a specific date. Thus, retained earnings appearing on the balance sheet are the profits of the business that remain after distributing dividends since its inception. The beginning period retained earnings appear on the previous year’s balance sheet under the shareholder’s equity section. The beginning period retained earnings are thus the retained earnings of the previous year.
Retained Earnings Guide: Formula & Examples
Whenever a company generates surplus income, a portion of the long-term shareholders may expect some regular income in the form of dividends as a reward for putting their money in the company. Traders who look for short-term gains may also prefer getting dividend payments that offer instant gains. Dividends are paid out from profits, and so reduce retained earnings for the company. Distribution of dividends to shareholders can be in the form of cash or stock. Cash dividends represent a cash outflow and are recorded as reductions in the cash account. These reduce the size of a company’s balance sheet and asset value as the company no longer owns part of its liquid assets.
- When evaluating the amount of retained earnings that a company has on its balance sheet, consider the points noted below.
- Both cash dividends and stock dividends result in a decrease in retained earnings.
- We can find the retained earnings (shown as reinvested earnings) on the equity section of the company’s balance sheet.
- Retained earnings are also called earnings surplus and represent reserve money, which is available to company management for reinvesting back into the business.
- It’s important to note that retained earnings are an accumulating balance within shareholder’s equity on the balance sheet.
Retained earnings appear on the balance sheet under the shareholders’ equity section. This statement of retained earnings can appear as a separate statement or as inclusion on either a balance sheet or an income statement. The statement is a financial document that includes information regarding a firm’s retained earnings, along with the net income and amounts distributed to stockholders in the form of dividends. An organization’s net income is noted, showing the amount that will be set aside to handle certain obligations outside of shareholder dividend payments, as well as any amount directed to cover any losses. Each statement covers a specified time period, as noted in the statement.
Benefits of a Statement of Retained Earnings
The steps to calculate a company’s retained earnings in the current period are as follows. Much like any other part of a business, there can be downsides to retained earnings. Retained earnings are a shaky source of funds because a business’s profits change. And it can pinpoint what business owners can and can’t do in the future.
You may use these earnings to further invest in the company or buy new equipment. You can also finance new products, pay debts, or pay stock or cash dividends. The retention ratio is the proportion What is Legal Accounting Software For Lawyers of earnings kept back in the business as retained earnings. It is the opposite of the payout ratio, which measures the percentage of profit paid out to shareholders as dividends.
Applications in Financial Modeling
If the balance of the retained earnings account is negative it may be called accumulated losses, retained losses or accumulated deficit, or similar terminology. As a result, the retention ratio helps investors determine a company’s reinvestment rate. However, companies that hoard too much profit might not be using their cash effectively and might be better https://turbo-tax.org/law-firm-finances-bookkeeping-accounting-and-kpis/ off had the money been invested in new equipment, technology, or expanding product lines. New companies typically don’t pay dividends since they’re still growing and need the capital to finance growth. However, established companies usually pay a portion of their retained earnings out as dividends while also reinvesting a portion back into the company.

It is calculated over a period of time (usually a couple of years) and assesses the change in stock price against the net earnings retained by the company. Retained earnings refer to the historical profits earned by a company, minus any dividends it paid in the past. To get a better understanding of what retained earnings can tell you, the following options broadly cover all possible uses that a company can make of its surplus money. For instance, the first option leads to the earnings money going out of the books and accounts of the business forever because dividend payments are irreversible. When a company loses money or pays dividends, it also loses its retained earnings. This is the company’s reserve money that management can reinvest into the business.
Example Retained Earnings Calculations
For smaller companies, this may be as easy as calculating the number of products sold by the sales price. For larger, more complex companies, this will be all units sold across all product lines. Both revenue and retained earnings can be important in evaluating a company’s financial management. As an investor, one would like to know much more—such as the returns that the retained earnings have generated and if they were better than any alternative investments. Additionally, investors may prefer to see larger dividends rather than significant annual increases to retained earnings. It involves paying out a nominal amount of dividends and retaining a good portion of the earnings, which offers a win-win.

Deprecated: Creation of dynamic property WP_Term::$cat_ID is deprecated in /home/uathvgwk/domains/rysiek.frydryk.pl/public_html/wp-includes/category.php on line 378
Deprecated: Creation of dynamic property WP_Term::$category_count is deprecated in /home/uathvgwk/domains/rysiek.frydryk.pl/public_html/wp-includes/category.php on line 379
Deprecated: Creation of dynamic property WP_Term::$category_description is deprecated in /home/uathvgwk/domains/rysiek.frydryk.pl/public_html/wp-includes/category.php on line 380
Deprecated: Creation of dynamic property WP_Term::$cat_name is deprecated in /home/uathvgwk/domains/rysiek.frydryk.pl/public_html/wp-includes/category.php on line 381
Deprecated: Creation of dynamic property WP_Term::$category_nicename is deprecated in /home/uathvgwk/domains/rysiek.frydryk.pl/public_html/wp-includes/category.php on line 382
Deprecated: Creation of dynamic property WP_Term::$category_parent is deprecated in /home/uathvgwk/domains/rysiek.frydryk.pl/public_html/wp-includes/category.php on line 383
Content
- What are some home business tax deductions?
- Stock Up and Pre-Pay Expenses
- Tax-Saving Moves You Can Make Before Year-End
- Businesses may depreciate property that meets all these requirements. The business must:
- Dental Transitions Services Social
- LLC Tax Extension
Inventory treated as non-incidental materials and supplies is used or consumed in your business in the year you provide the inventory to your customers. Under an accrual method of accounting, you generally deduct or capitalize a business expense when both the following apply. The following are special rules that apply to advance payments, estimating income, and changing a payment schedule for services. For 2022, you received one credit, up to a maximum of four credits, for each $1,510 ($1,640 for 2023) of income subject to social security taxes. Therefore, for 2022, if you had income (self-employment and wages) of $6,040 that was subject to social security taxes, you receive four credits ($6,040 ÷ $1,510). To make this election, you must divide all items of income, gain, loss, deduction, and credit attributable to the business between you and your spouse in accordance with your respective interests in the venture.
- Failure to provide this level of funding for the company could leave the owner liable for all of the company’s debt in bankruptcy court under the theory of undercapitalization.
- To find a list of current state tax deadlines, click here.
- As WHD authorized representatives, they conduct investigations and gather data on wages, hours, and other employment conditions in order to determine compliance with the law regardless of workers’ immigration status.
- Go to TaxpayerAdvocate.IRS.gov to help you understand what these rights mean to you and how they apply.
- Most tax filers will receive their refund within 21 calendar days after their return was received by the IRS.
These may seem like mundane tasks, but these systems break all the time. As your digital calling card and first impression of your business, your website is an important commodity to keep in fine working order. In a world driven by e-commerce, it’s more important than ever to have a solid website for your business.
What are some home business tax deductions?
SCORE is made up of current and former business people who offer their expertise and knowledge to help people start, manage, and expand a small business. SCORE also offers a variety of small business workshops. The IRS is committed to serving our multilingual End Of Year And Beyond Small Business Tax Tips customers by offering OPI services. The OPI Service is a federally funded program and is available at Taxpayer Assistance Centers (TACs), other IRS offices, and every VITA/TCE return site. The OPI Service is accessible in more than 350 languages.

For more information, see When To File in the form instructions. If your lessee makes payments to someone else under an agreement to pay your debts or obligations, include the payments in your gross receipts when the lessee makes the payments. A common example of this kind of income is a lessee’s payment of your property taxes on leased real property.
Stock Up and Pre-Pay Expenses
If you hold stock as a personal investment separately from your business activity, the dividends from the stock are nonbusiness income. Advance payments received under a lease that does not put any restriction on their use or enjoyment are income in the year you receive them. This is generally true no matter what accounting method or period you use. You are a real estate dealer if you are engaged in the business of selling real estate to customers with the purpose of making a profit from those sales. Rent you receive from real estate held for sale to customers is subject to SE tax.
She must use the regular method to figure her net earnings. She cannot use the nonfarm optional method because her net profit is not less than 72.189% of her gross income. You are subject to SE tax if you are an employee of a state or local government, are paid solely on a fee basis, and your services are not covered under a federal-state social security agreement. Generally, resident aliens must pay SE tax under the same rules that apply to U.S. citizens.
Tax-Saving Moves You Can Make Before Year-End
In any case, it’s essential to consult with a tax professional to fully understand your tax obligations and ensure compliance with both state and federal tax laws. It’s always better to file a return, even if it’s just to report no activity, than to risk penalties for failing to file. Remember, this extension is only for filing the tax return, not for paying any taxes owed. https://kelleysbookkeeping.com/ If you can’t pay the full amount, it’s generally advisable to pay as much as you can to limit potential interest and penalties. Many high-income earners either don’t use an HSA at all or they use it incorrectly. If you qualify for a Health Savings Account, consider investing your HSA contributions for the long-term instead of spending them on current medical expenses.
- Putting money into a tax-deferred retirement plan will lower your taxes — even if you just contributing to the minimum.
- Every year there are tax modifications, as well as new procedures and deductions.
- WHD does not consider filing of a comment with the Ombudsman as a factor in determining how to resolve issues raised during a compliance action.
- We will send you a letter with either a request for more information or a reason why we believe a change to your return may be needed.
- Your “net operating loss” (NOL) carryforward — meaning the amount that went unused in the previous year — is now limited to 80% of your taxable income.
When in doubt, remember this guideline, and hang onto the receipts attached to any business related expenditure. That way you can (and should) double check with your CPA to confirm what is, and what isn’t, tax deductible before you file your return. But even less specific forms of education—for instance, a photography class that helps you take better pictures of the products you sell—can be deducted. So long as the class directly improves your day-to-day business operations, it’s tax deductible. The IRS has a reputation for carefully scrutinizing home office expenses. Make sure you have the info you need to back up your claim.
]]>Deprecated: Creation of dynamic property WP_Term::$cat_ID is deprecated in /home/uathvgwk/domains/rysiek.frydryk.pl/public_html/wp-includes/category.php on line 378
Deprecated: Creation of dynamic property WP_Term::$category_count is deprecated in /home/uathvgwk/domains/rysiek.frydryk.pl/public_html/wp-includes/category.php on line 379
Deprecated: Creation of dynamic property WP_Term::$category_description is deprecated in /home/uathvgwk/domains/rysiek.frydryk.pl/public_html/wp-includes/category.php on line 380
Deprecated: Creation of dynamic property WP_Term::$cat_name is deprecated in /home/uathvgwk/domains/rysiek.frydryk.pl/public_html/wp-includes/category.php on line 381
Deprecated: Creation of dynamic property WP_Term::$category_nicename is deprecated in /home/uathvgwk/domains/rysiek.frydryk.pl/public_html/wp-includes/category.php on line 382
Deprecated: Creation of dynamic property WP_Term::$category_parent is deprecated in /home/uathvgwk/domains/rysiek.frydryk.pl/public_html/wp-includes/category.php on line 383
Content
- Take the Exam
- What’s a Typical Day for a Bookkeeper?
- Powerful Marketing Tips For Accounting Firms
- Online Training
- Learn more about QuickBooks Online in our free on-demand webinars
- Career Paths
- Why Your Company Needs „Great Bookkeeping”
There’s expert guidance on cash flow, and how to create statements of cash flow in QuickBooks online. Plus, there are quizzes to test your knowledge of cash flow interpretation. The 18 hours of resources guide students through the process of using bank reconciliations to control cash flow, outlining financial statements, and applying quantitative skills to business health.
You will receive an „Acclaim” badge which can be added to your LinkedIn profile to prove that you are certified. If you have done the training with us, our facilitator will let you know when Independent Contractor Agreement for Accountants and Bookkeepers you are ready. If you have prepared for this exam yourself, you are can do the practice exams aligned to this exam as practice and to get a good idea if you are ready for your exam.
Take the Exam
Yes, if you’re an expert in the latest version of QuickBooks, you can walk into any small business and immediately organize their finances. QuickBooks is the top-rated accounting software for small businesses, you likely know a company that already uses it. Bookkeepers serve on the front lines of a person, company or organization’s financial health. Strong bookkeepers set up, deploy and manage systems that record the flow of funds into and out of an entity’s coffers. Using reporting tools and systems, bookkeepers help individuals and operational managers stay aware of and improve an entity’s financial status and performance. When you enroll in this self-paced certificate program, you decide how quickly you want to complete each of the courses in the specialization.
- The following are examples of bookkeeping organisations that provide a host of bookkeeping programs to help you learn and enhance your bookkeeping knowledge.
- The two totals must agree—which is not by chance—because under the double-entry rules, whenever there is a posting, the debits of the posting equal the credits of the posting.
- Professionals in the accounting field who add a certification to their professional qualifications can appeal to more potential employers.
- A Bachelor’s Degree in Accounting can provide you with the fundamental knowledge necessary to start advising businesses, individuals, and organisations in financial and accounting matters.
- He has previously served as an instructor for courses at Coopers & Lybrand and UC San Diego and is currently an adjunct professor at the University of San Diego School of Business.
- He is currently Director of Finance and Administration for New Children’s Museum.
Of course, a background in accounting practices will help you ride out a learning curve as a new bookkeeper. A bookkeeper is skilled at keeping documents and tracks a wide net of financial information. Bookkeeping is a great starting point if you are interested in the field but not fully committed and want to test the waters. You may also be an ideal bookkeeping candidate if you want a good job with a respectable wage and decent security but may not be looking for a long-term career.
What’s a Typical Day for a Bookkeeper?
When you register for the CB exam, consider adding a few of AIPB’s official workbooks to your order form. The six official CB workbooks range from $29 to $49 each for members ($39-$59 for non-members), containing sections on every exam topic. Quizzes included throughout the workbooks help ensure information mastery. Explore programs of your interests with the high-quality standards and flexibility you need to take your career to the next level. Whether you are a small business owner or a bookkeeper or an adviser trying to help clients grow, the QuickBooks Community is a good platform to get your queries answered. Global QuickBooks Community is an online hub that allows you to connect with other QuickBooks users around the world.
What is the job description of a bookkeeper?
A bookkeeper is responsible for recording and maintaining a company's daily financial transactions. They also prepare reports for the managers and trial balances to assist the accountants. A bookkeeper may also help you run payroll, collect debts, generate invoices and make payments.
These professionals can give you accounting and bookkeeping tips and tricks from their own experience. As a bookkeeper, you are responsible for maintaining accurate financial records and handling all the accounting processes for a business. Professionals in the accounting field who add a certification to their professional qualifications can appeal to more potential employers.
Powerful Marketing Tips For Accounting Firms
Whether you want to develop the skills of bookkeeping or further your career in business, there are critical accounting and bookkeeping concepts to be learned. With this knowledge in hand you will be able to provide professional bookkeeping services for a wide range of businesses. Bookkeepers can also obtain additional certification showing their mastery of Intuit QuickBooks, the most popular accounting software for small businesses. Consider taking the QuickBooks certified user exam or pursuing the Intuit certified bookkeeping professional credential.
You will be able to write this exam remotely online if you have a stable internet connection and your own computer. You will also be able to come in to write your exam on the computers in the Stellietech Stellenbosch testing centre. If you have an existing account with Franklin University but are unable to log in, you can recover a lost or forgotten username/password with the ACCOUNT RECOVERY button. Learn about tuition, scholarships, and other financial aid opportunities. This course is accredited and comes with a certification to share on your resume. He has more than 18 years of practical experience with SEO and digital marketing.
Online Training
The distinctions between accounting and bookkeeping are subtle yet essential. The two careers are similar, and accountants and bookkeepers often work side by side. However, significant differences exist, like work conducted in each career and needed to be successful. The following analysis compares the education requirements, skills required, typical starting salaries, and job outlooks for accounting and bookkeepers. It also includes all of the information students need to take the Intuit exam for certified https://accounting-services.net/what-is-the-difference-between-bookkeeping-and/s, with hands-on projects and resources.
- Furthermore, it also gives you a practice test which is a great way to get ready for the exam.
- Though licensure is not required to work as a bookkeeper, some professionals pursue certification to demonstrate their skills to employers and stand out in the job search.
- Stellietech will email you your E-Certificate and Score Report in the meantime as soon as it is ready.
- Such an association helps bookkeepers develop knowledge and skill via bookkeeping education and accreditation.
Deprecated: Creation of dynamic property WP_Term::$cat_ID is deprecated in /home/uathvgwk/domains/rysiek.frydryk.pl/public_html/wp-includes/category.php on line 378
Deprecated: Creation of dynamic property WP_Term::$category_count is deprecated in /home/uathvgwk/domains/rysiek.frydryk.pl/public_html/wp-includes/category.php on line 379
Deprecated: Creation of dynamic property WP_Term::$category_description is deprecated in /home/uathvgwk/domains/rysiek.frydryk.pl/public_html/wp-includes/category.php on line 380
Deprecated: Creation of dynamic property WP_Term::$cat_name is deprecated in /home/uathvgwk/domains/rysiek.frydryk.pl/public_html/wp-includes/category.php on line 381
Deprecated: Creation of dynamic property WP_Term::$category_nicename is deprecated in /home/uathvgwk/domains/rysiek.frydryk.pl/public_html/wp-includes/category.php on line 382
Deprecated: Creation of dynamic property WP_Term::$category_parent is deprecated in /home/uathvgwk/domains/rysiek.frydryk.pl/public_html/wp-includes/category.php on line 383
Content
- Finding a Nonprofit Consultant: 5 Tips to Get the Best Fit
- How To Do Bookkeeping For Nonprofits
- What does a Bookkeeper do for a Nonprofit?
- A consistent source of support for your board
- Nonprofit Budget
- of the Best Accounting Software for Nonprofits
And it doesn’t mean that all of the activities your nonprofit spends money on aren’t taxable. Tax-exempt nonprofit employees are still subject to employment taxes, and your nonprofit could still be subject to sales, real estate and other taxes depending on which state it’s based in. Just like the statement of financial position, the statement of activities keeps net assets that have conditions and stipulations attached to them separate from unrestricted funds. The difference between the balance sheet and the statement of financial position is that, because nonprofits don’t technically have any owners, the statement of financial position doesn’t have any equity on it.
- Implementing internal controls and policies, your nonprofit can take the first step to protect itself against fraud.
- Each of these funds needs to be individually balanced and records need to be kept in separate ledgers.
- Creating financial statements is crucial for understanding how much money the nonprofit has accrued, how funds are allocated across bank accounts, and how money got in each account.
- They help select and purchase QuickBooks software, train your team to use financial software, or perform the accounting activities on your behalf.
- A key benefit of Outsourcing is that it gives you the ability to customize the services with your bookkeeping needs.
- An employer identification number, or tax identification number, works as your unique ID recognizing the nonprofit as a business entity.
We recommend doing a bank reconciliation at least once a month to make sure your books are up to date and accurate, to help track cash flow, to prevent fraud and to detect bank errors. Most nonprofits elect some kind of treasurer or financial officer to manage all of the organization’s https://adprun.net/bookminders-outsourced-accounting-and-bookkeeping/ finances. Using a personal bank account and keeping a shoebox full of receipts isn’t going to cut it. Our professional opinion is that the majority of nonprofits will benefit from outsourcing their bookkeeping and accounting needs, working directly with nonprofit accounting experts.
Finding a Nonprofit Consultant: 5 Tips to Get the Best Fit
These accounting software programs are designed to streamline your nonprofit’s bookkeeping and financial reporting processes while keeping you compliant with IRS standards. MIP is today’s leading accounting software for nonprofits and government organizations across the nation. Designed to let you track unlimited funds and manage your books with ease, MIP Fund Accounting® software offers a simple way to manage intricate financial processes in a single, user-friendly system. With no payroll tools, Quicken allows solo-run nonprofits that rely on volunteers to perform basic business accounting, such as allocating funds based on donor intent to different categories or budgets.
For large or growing organizations who need comprehensive accounting services, this program can be a good fit. A nonprofit’s statement of financial position is similar to a for-profit’s balance sheet. Unlike for-profits, a nonprofit does not have A Guide to Nonprofit Accounting for Non-Accountants ‘equity’ but ‘net assets.’ Net assets are left after subtracting liabilities from assets. Most nonprofit-friendly accounting software like QuickBooks Aplos or Nonprofit Treasurer will allow you to generate financial statements automatically.
How To Do Bookkeeping For Nonprofits
The selected program should be able to automate everyday tasks and minimize errors. FreshBooks accounting software accomplishes all of these tasks with ease and is an excellent choice depending on your needs. For-profit entities are individuals, corporations, or partnerships that conduct business for profit. In this case, shareholders, investors, tax authorities, management, and suppliers are interested in the entity’s financial position, and that’s what for-profit accounting focuses on.
]]>Deprecated: Creation of dynamic property WP_Term::$cat_ID is deprecated in /home/uathvgwk/domains/rysiek.frydryk.pl/public_html/wp-includes/category.php on line 378
Deprecated: Creation of dynamic property WP_Term::$category_count is deprecated in /home/uathvgwk/domains/rysiek.frydryk.pl/public_html/wp-includes/category.php on line 379
Deprecated: Creation of dynamic property WP_Term::$category_description is deprecated in /home/uathvgwk/domains/rysiek.frydryk.pl/public_html/wp-includes/category.php on line 380
Deprecated: Creation of dynamic property WP_Term::$cat_name is deprecated in /home/uathvgwk/domains/rysiek.frydryk.pl/public_html/wp-includes/category.php on line 381
Deprecated: Creation of dynamic property WP_Term::$category_nicename is deprecated in /home/uathvgwk/domains/rysiek.frydryk.pl/public_html/wp-includes/category.php on line 382
Deprecated: Creation of dynamic property WP_Term::$category_parent is deprecated in /home/uathvgwk/domains/rysiek.frydryk.pl/public_html/wp-includes/category.php on line 383
Content
- Don’t miss out on tax deductions for volunteering
- The Short Form: Understanding the House GOP Tax Plan
- Tangible personal property
- Schwab has solutions for charitable giving.
- What can you take a tax deduction for?
The IRS doesn’t have any stated amounts considered acceptable for these items. The guide tells you the average prices of clothing, furniture, and household items in its stores. If you accept something in return for your gift, you can’t write off the full amount. Filing away this information right away makes tax season easier and also keeps you prepared in case of a future audit.
- Large charitable gifts should also be planned carefully in order to maximize the deduction and minimize your out-of-pocket cost.
- For the tax year 2023 (returns are typically filed in 2024), the standard deduction goes up considerably, due to inflation.
- It’s a good idea to speak with a tax professional to determine the amount you can claim.
- Donating your stocks directly to a charity may offer more tax benefits and can lower your tax bracket.
- Nonprofits, for instance, may seek government funding for an activity, or its members may engage in debates with government officials, though various rules limit outright lobbying.
- As lawmakers crafted the TCJA, they were very clear that one of the goals was to reduce marginal income tax rates.
- Donor-advised funds like Daffy make bunching charitable contributions easy because you can first contribute the amount you’d like to bunch to your Daffy fund and immediately receive the tax deduction for that amount.
If the charity sells the vehicle, the charity must send you a Form 1098-C within 30 days of the sale. You can also deduct the cost of driving to and from your volunteer work, at a rate of 14 cents per mile in 2022. If you take public transportation, that bus or rail fare is deductible, https://turbo-tax.org/ too. Let’s say you own stock that you bought many years ago for $1,000 that is now worth $10,000, and that you intend to make a $10,000 gift to a major fundraiser for your alma mater. If you write a check for $10,000, the college gets $10,000, and you get to deduct $10,000.
Don’t miss out on tax deductions for volunteering
While tax breaks typically aren’t the main reason for giving, experts say some donors may be missing out on the chance for a deduction. Our team of skilled tax and accounting professionals is prepared to assist you with your business objectives, whether it’s a brief meeting, consultation, or in-depth audit. For example, if your rate is 32% and you contributed $10,000 in cash, goods or both, you’ll end up saving $3,200 at tax time.

Generally, you’d itemize when the combined total of your anticipated deductions—including charitable gifts—add up to more than the standard deduction. In order to understand the impact this new law has on charitable giving, it’s important to understand the relationship between the standard deduction and itemized deductions such as charitable contributions. Charitable donations to eligible 501(c)(3) non-profit organization, such as Save the Children continue to be itemized deductions which may reduce your taxable income. Before you claim a charitable donation on your tax return—or, even better, before you make a donation at all—check with the IRS to see whether the organization you’re supporting qualifies as tax exempt. The organization itself may be able to provide this information; the IRS also maintains a search tool you can use to verify an organization’s tax exempt status.
The Short Form: Understanding the House GOP Tax Plan
In addition to federal taxes, your income is also subject to state taxes, unless you live in one of the nine states that don’t charge income tax. In California, for instance, the highest bracket for single filers earning $1 million or more and married couples earning $2 million or more is 13.3%. Typically, if you sell stock you held for longer than a year at a profit, you would need to pay capital gain taxes. Generally, the amount you can deduct on your taxes is the fair market value of the property you donate, or the cash value.
Are donations to Ukraine tax deductible?
Donations to registered Ukrainian charities and not-for-profit organisations are deductible in an amount that is not higher than 4% of the taxpayer's taxable income. For the tax year 2022, this limit was increased to 16%.
The standard deduction for married couples filing jointly for the tax year 2023 is $27,700. For single taxpayers and married individuals filing separately, the standard deduction rises to $13,850, and for heads of households, the standard deduction will be $20,800 for the tax year 2023. Tax law requires that deductions are allowed only for contributions that serve a charitable purpose. A recipient organization must qualify for tax-exempt status as required by the tax code and determined by the Internal Revenue Service (IRS).
Tangible personal property
Many non-profit advocates feared that contributions would decline if there were fewer taxpayers able to deduct their charitable donations. However, according to Giving USA data, total individual giving did not drop off much following the TCJA, in both nominal or real terms. Indeed, in real terms, individual giving in 2018 was higher than 2016 levels (pre-TCJA). As Table 2 illustrates, the number of itemizers who claimed the charitable deduction dropped significantly from roughly 38 million in 2017 to nearly 15 million in 2018, a 60 percent decline. As a result, IRS data shows that the overall value of itemized charitable deductions fell from $256 billion in 2017 to $196 billion in 2018. Many taxpayers took advantage of these prospective changes by increasing their charitable gifts in 2017 to deduct them at the higher tax rates.
The tax law that took effect in 2018 nearly doubled the standard deduction and limited the state and local tax deduction, making it harder for taxpayers to itemize. If your total deduction for non-cash contributions exceeds $500, you must fill out Form 8283, Section A – eFileIT – which eFile.com will do for you. If your contribution of non-cash property exceeds $5,000, you may be required to obtain a third-party appraisal of the value. If that is the case, you will also have to fill out Form 8283, Section B – eFileIT. Remember that eFile.com will generate the correct forms for you during your online tax preparation process. If the value of a single donation exceeds $250, you must acquire written acknowledgment from the qualified organization.
Raising the Standard Deduction Removed 46 Million Itemizers
You are allowed to donate goods at their estimated value at the time of donation, not at the value they had when first purchased. For donations worth less than $250, you must get a written receipt from the organization as well as prepare a list of items donated and their value. If https://turbo-tax.org/charitable-contributions-and-your-taxes/ you want to save money on taxes, be charitable, and clean out your basement at the same time, you can donate household goods as well. There are many charities and church organizations that accept donations of clothing and household items to give away or resell to those in need.
- Charitable donations of both money and goods to qualified organizations can be deducted on your income taxes, lowering your taxable income.
- Yes, it’s possible to deduct the full fair market value of the contribution if the recipient organization is a public charity.
- By disregarding Sec. 170(c)(2)(A), Sec. 642(c) indicates that a foreign organization organized and operated exclusively for a charitable purpose is an eligible donee for a charitable deduction for a trust or estate.
- The guide tells you the average prices of clothing, furniture, and household items in its stores.
- Donating property can earn you a deduction just as donating money can.
Examples provided are for illustrative purposes only and not intended to be reflective of results you can expect to achieve. The example is hypothetical and provided for illustrative purposes only. Please check your e-mail and click on the secured link to verify your request. Please check your e-mail and click on the secured link to verify your subscription. If you are an individual investor and have an account with US Charitable Gift Trust, sign into your account here. Please click here to receive a new link to access the requested content.
Schwab has solutions for charitable giving.
Some donations fund activities that substitute for those the government might otherwise undertake. Other donations complement government activities, and still others support an adversarial relationship with government. Nonprofits, for instance, may seek government funding for an activity, or its members may engage in debates with government officials, though various rules limit outright lobbying. Many believe these types of charitable activity make democracies healthier, even when particular chartable efforts have little impact. Former President Donald Trump’s signature 2017 tax overhaul nearly doubled the standard deduction, making filers less likely to itemize.

Managing that requirement may be easier if you donate by check or credit card. You can’t deduct the value of volunteer hours and, generally speaking, your donation can’t be made in exchange for something of value. Political contributions—either to a candidate or a cause—are also not deductible.
How much can you claim in charitable donations without receipts?
More clear, however, is how taxpayers with incomes above $10 million responded to the CARES Act expansion of the deduction limitation. This also gives you the opportunity to augment your donations in a particular tax year for tax-deduction purposes. To increase his deductions last year, Parrish gave away a recreational vehicle, and the organization receiving it sold it and sent him a qualified appraisal for his records. The IRS also provides a tool, Tax Exempt Organization Search, where you can confirm the status of a tax-exempt organization. Other online databases to check include GuideStar and Charity Navigator.
What is the first dollar out rule?
Background: As we have covered in the past, the first-dollars-out rule provides that when a required minimum distribution (RMD) obligation exists, e.g. after the IRA owner or plan participant attains age 72, those dollars receive from the retirement plan are not eligible to be rolled over until the owner/participant's …